IRA PLANS

Payroll Deduction IRAs for Small Businesses

Give your team an easy way to save for retirement with a Payroll Deductible IRA. Simple to set up and effortless to manage, it combines self-directed alternative investing and AI-powered trading to help your employees build their future as your business grows.

Why a Payroll Deductible IRA at IRA Club SBS?

Payroll Deduction IRA Support

Lead Your Team Forward with Protected AI Investing

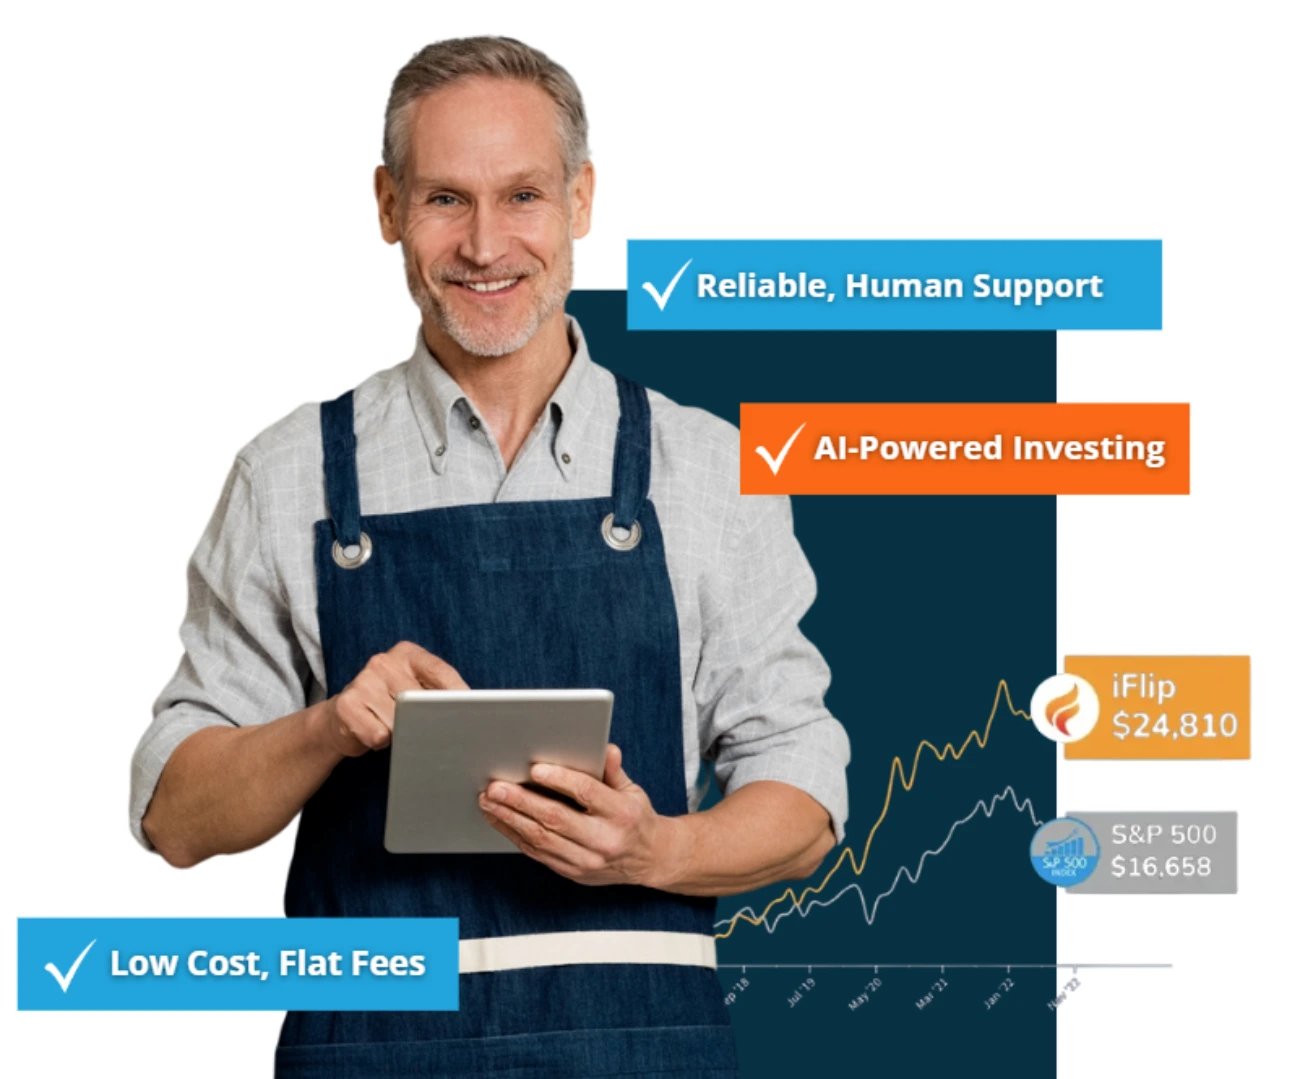
Empower your employees with access to an AI-powered investing platform built to protect and grow wealth, at a cost that’s up to 6x lower than the industry standard.

Annual pricing: $950 plus $40 per active participant.

Wealth Manager Robo Advisor Online Broker
Investments managed with AI
Can choose market index strategy
Low minimum investment ($500)
Ability to pay 0% in fees
Built with protection in mind
Intuitive online experience
Choose individual stocks or ETFs

Alternative Investment Options With a Payroll Deduction IRA

With IRA Club SBS, your employees can access alternative investment options beyond traditional stocks and bonds, including: 

SEP IRA real estate - icon

Real Estate

Retirement plan forms icon

Private Lending

SEP IRA syndications icon image

Syndications

SEP IRA syndications icon image

Cryptocurrency

SEP IRA syndications icon image

Private Placement

SEP IRA syndications icon image

Precious Metals

Connect with Your Payroll Provider

Find my payroll provider

Can’t find your payroll provider? Give us a call

Can’t find your payroll provider? 
Give us a call

Frequently Asked Questions

What is a payroll deduction IRA, and how does it work?

A payroll deduction IRA is a streamlined retirement savings option where employees open a Traditional or Roth IRA with a financial institution and authorize automatic contributions directly from their paycheck. This makes saving simple and consistent — contributions are deducted before or after tax (depending on the IRA type) and deposited into the employee’s individual account each pay period.

Any employee who performs services for the company can participate if the employer offers a payroll deduction IRA program. Employers must offer it uniformly; it cannot be limited by job title, tenure, or classification. This flexibility makes it ideal for small businesses seeking an easy retirement benefit.

For 2026, the annual IRA contribution limit is $7,500 for individuals under age 50 and $8,100 for those age 50 and over (including the $1,100 catch-up contribution). Traditional and Roth IRAs share this combined limit, regardless of how the contributions are made (through payroll or direct deposit). These limits are set by the IRS and typically adjust annually for inflation.

A payroll deduction IRA allows only employee contributions via payroll; employers do not contribute funds. Employers simply facilitate the withholding and remittance of employee-authorized contributions. An employer-sponsored IRA plan (like a SEP or SIMPLE IRA) may include employer contributions and has additional IRS reporting or matching requirements.

Yes. Employees select whether their payroll deductions go into a Traditional (pre-tax) IRA or a Roth (after-tax) IRA based on their personal tax strategy and eligibility. Employees may also change their choice during the year as long as payroll instructions are updated.

Employees open an IRA with IRA Club SBS, then authorize their employer to deduct a chosen amount from each paycheck. Contribution amounts can be changed or stopped at any time by notifying the employer or payroll provider.

At IRA Club SBS, our systems integrate with iFlip, an AI-powered investing platform that adapts to today’s unpredictable markets, letting you and your team invest confidently without timing the market or paying high advisor fees. Additionally, alternative investments such as real estate, private equity, precious metals, cryptocurrencies, tax liens, and private loans are permitted. IRA Club SBS is not licensed to provide investment or structuring advice or make recommendations; employees must find their own alternative investments and conduct their own due diligence. See “alternative investing” for details.

Traditional IRA contributions may be tax-deductible, offering immediate tax benefits. Roth IRA contributions are made with after-tax dollars and grow tax-free, but are not deductible.

Withdrawals from a Traditional IRA before age 59½ are subject to income tax and a 10% early withdrawal penalty. Roth IRA contributions can be withdrawn penalty-free at any time, but unqualified earnings withdrawn before 59 ½ may incur taxes and penalties.

Why should I, as a small business owner, offer payroll deduction IRAs to employees?

Payroll deduction IRAs are easy to set up, require minimal administration, and help employees save for retirement. They offer a valuable benefit without employer contributions or complex reporting requirements, making them ideal for small businesses. Contact our onboarding specialist at IRA Club SBS here.

A payroll deduction IRA may or may not satisfy a state retirement mandate. Each state defines which employer arrangements qualify for an exemption, and some programs may not treat an employee-owned payroll deduction IRA as a qualifying employer plan. Your state program determines whether your arrangement qualifies and what exemption steps apply. A [SIMPLE IRA] is an employer-sponsored plan, but its treatment must also be confirmed under the applicable state rules.

Scroll to Top